Key Highlights
- European equity markets climbed approximately 1% on Monday, driven by declining crude oil prices that reduced inflation concerns and improved corporate profitability outlooks.
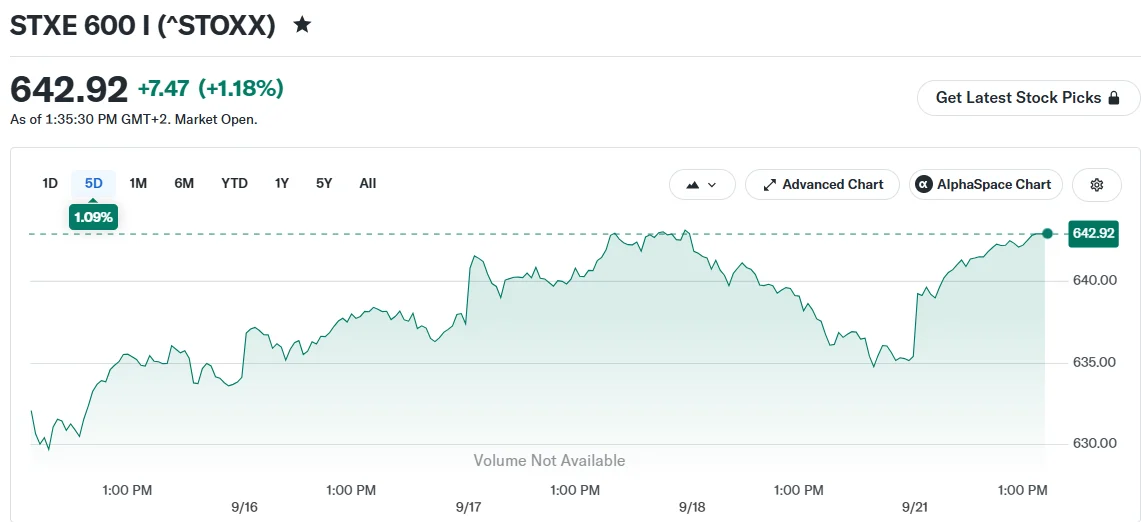
- The STOXX 600 index recorded its most significant single-day rally in over two months.
- Germany’s DAX index advanced even as Chancellor Friedrich Merz’s political party experienced its poorest state election outcome in more than seven decades.
- Tech sector equities dominated gains, with notable increases from ASML and Soitec.
- Market participants remain focused on ECB commentary for signals regarding the continuation of monetary tightening.
European stocks experienced substantial gains on Monday as declining energy prices enabled traders to overlook political challenges in Germany and mounting interest rate anxieties.
The STOXX 600 index climbed approximately 1%, registering its most robust single-day performance in over eight weeks.
French CAC 40, Italian FTSE MIB, and Spanish IBEX 35 indices similarly posted gains near 1%.
The FTSE 100 in London advanced nearly 1%, though weakness in energy sector holdings tempered the overall advance.
Crude Price Decline Provides Market Support
The primary catalyst for equity strength came from continued weakness in oil markets.
Oil prices decreased for the fourth consecutive trading session as market participants monitored potential diplomatic developments in Middle Eastern affairs.
President Donald Trump indicated openness to a potential meeting with Iranian President Masoud Pezeshkian during this week’s United Nations General Assembly gathering.
Decreasing energy costs can alleviate inflationary pressures while enhancing profit margins for energy-dependent corporations.
This dynamic enabled European markets to rebound following Friday’s downturn.
The STOXX 600 had retreated 0.33% during the previous week, extending its losing streak to three consecutive weeks.
Friday’s decline stemmed from concerns regarding European crude availability after Saudi Aramco suspended certain allocations following attacks targeting its East-West pipeline infrastructure.
DAX Advances Despite Political Headwinds in Germany
Germany’s DAX index climbed roughly 1% notwithstanding a challenging weekend for Chancellor Friedrich Merz.
Merz’s conservative political party posted its most disappointing state election results since 1949.
The outcome generated uncertainty about coalition government stability and the administration’s capacity to implement economic reform measures.
Deutsche Bank analysts noted that immediate market implications centered less on national policy shifts and more on the erosion of Germany’s political center.
Technology equities helped counterbalance these political concerns.
Soitec shares surged over 7%, while ASML climbed approximately 4% following positive momentum in Asian technology markets.
Novo Nordisk moved contrary to the broader trend, declining more than 5% after presenting its extended-term growth outlook.
ECB Monetary Policy Direction Under Scrutiny
Investors continue monitoring statements from European Central Bank representatives.
ECB President Christine Lagarde and Executive Board member Piero Cipollone are scheduled to deliver remarks later Monday.
Markets seek clarity on whether the ECB’s recent rate adjustment to 2.50% represented an isolated response to inflation and energy challenges or signals the beginning of an extended tightening phase.
Eurozone inflation figures remain elevated above target levels, maintaining pressure on monetary authorities.
Bond markets have already responded to the latest rate decision, and investors maintain heightened sensitivity to any suggestions that borrowing costs could remain elevated longer.
Individual equity performance showed significant variation.
Elixirr International shares dropped substantially after disclosing weaker organic growth figures.
Ayvens declined despite announcing an improved 2029 return-on-tangible-equity forecast.
Currently, decreasing oil prices combined with technology sector strength continue supporting European equity markets, even as investors track German political developments and anticipate the ECB’s forthcoming actions.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants