


TLDR
- European equity markets advanced on Wednesday, with the STOXX 600 climbing 0.7% following two days of stagnant trading.
- Both Germany’s DAX and London’s FTSE 100 posted 0.7% gains throughout the trading day.
- Technology and semiconductor equipment shares drove the rally after President Trump endorsed voluntary artificial intelligence safety frameworks.
- Trump’s confirmation of support for accelerated data center construction alleviated concerns regarding potential technology sector spending reductions.
- Notwithstanding Wednesday’s positive performance, the STOXX 600 approaches a nearly 2% September decline, marking its first monthly loss in half a year.
European stock markets advanced on Wednesday as market participants positioned themselves ahead of a packed calendar of economic indicators from Europe and the United States.
The pan-European STOXX 600 benchmark climbed 0.7%, breaking a two-session stretch of minimal movement.
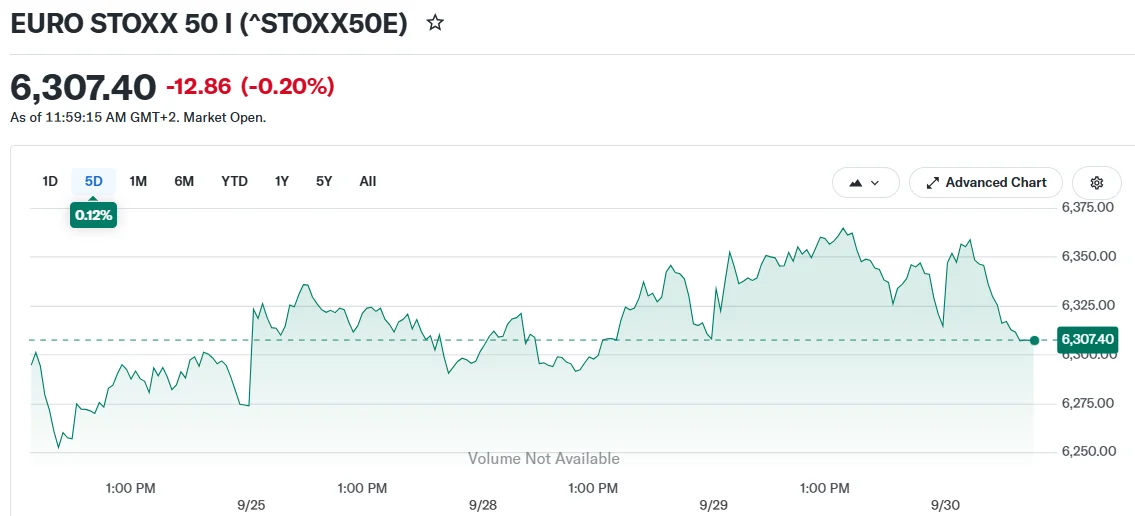
Germany’s DAX index and London’s FTSE 100 each posted 0.7% advances during the session. The STOXX 50 similarly pushed higher, adding 0.5% to reach its strongest level in three weeks.
Technology Sector Powers Market Recovery
Technology and semiconductor equipment firms ranked among the session’s strongest performers. The rally followed statements from President Donald Trump indicating that prominent technology leaders had committed to voluntary safety protocols for artificial intelligence development.
Trump additionally reaffirmed his commitment to expediting data center construction. This announcement calmed investor anxieties that corporations might scale back expenditures following recent AI model training suspensions at OpenAI.
Hardware manufacturers and energy providers captured the greatest benefits from these developments. Market participants had expressed concern that regulatory measures might impede data center expansion, though Trump’s statements alleviated those fears.
ASML shares advanced 0.8%. Novartis climbed 1.1%, while Airbus and Safran posted increases of 1.3% and 1.2% respectively.
However, not all companies participated in the rally. TotalEnergies shares declined 1% as the energy sector shifted into negative territory by day’s end.
Market Focus Shifts to Inflation Indicators
Beyond technology stocks, market participants are monitoring a comprehensive array of economic releases. These encompass German retail sales data for August and German labor market statistics.
French inflation figures and September German inflation data are scheduled for release later today. These metrics will provide investors insight into regional pricing dynamics.
In the United States, focus centers on the August Personal Consumption Expenditures price index, which serves as the Federal Reserve’s primary inflation gauge.
Economic analysts anticipate the index will demonstrate that inflationary pressures remained flat compared to the prior month. A stable reading would constitute favorable news for interest rate-sensitive equity sectors.
U.S. Treasury yields have been hovering near multi-decade peaks. A consistent inflation figure could reinforce expectations that the Federal Reserve need not implement additional rate increases beyond current market projections.
Market participants are additionally awaiting commentary from European Central Bank official Frank Elderson scheduled for later today. His statements may provide fresh perspective regarding eurozone economic expansion forecasts.
Monthly Performance Shows Decline Despite Daily Gains
Notwithstanding Wednesday’s positive session, September has proven challenging for European equities broadly. The STOXX 600 is positioned to conclude the month with approximately a 2% loss.
This would represent the index’s first monthly retreat in six months, following a summer characterized by European market strength.
Multiple headwinds pressured equities throughout September. These encompass ascending government bond yields, elevated energy expenses, and continued turbulence within the artificial intelligence industry.
Energy prices have surged again this month, attributed partially to stalled negotiations between the United States and Iran, which has intensified inflation concerns.
Examining the third quarter comprehensively, the STOXX 50 remains essentially flat. The STOXX 600 has declined 0.6% across the identical timeframe.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


