Key Highlights
- British equities declined 0.60% on Tuesday amid a surge in oil prices and growing concerns over artificial intelligence regulation
- UK payroll employment decreased by 26,000 workers in August, continuing July’s revised 19,000 decline
- The unemployment rate remained steady at 4.9% for the fourth consecutive month, staying below anticipated 5% levels
- Brent crude climbed to $107.42 per barrel following a pipeline disruption in Saudi Arabia that affected supply chains
- Market analysts anticipate the Bank of England will maintain its 3.75% interest rate following Tuesday’s disappointing employment figures
London’s equity markets experienced downward pressure on Tuesday as energy prices climbed and ongoing discussions about artificial intelligence oversight dampened investor confidence.
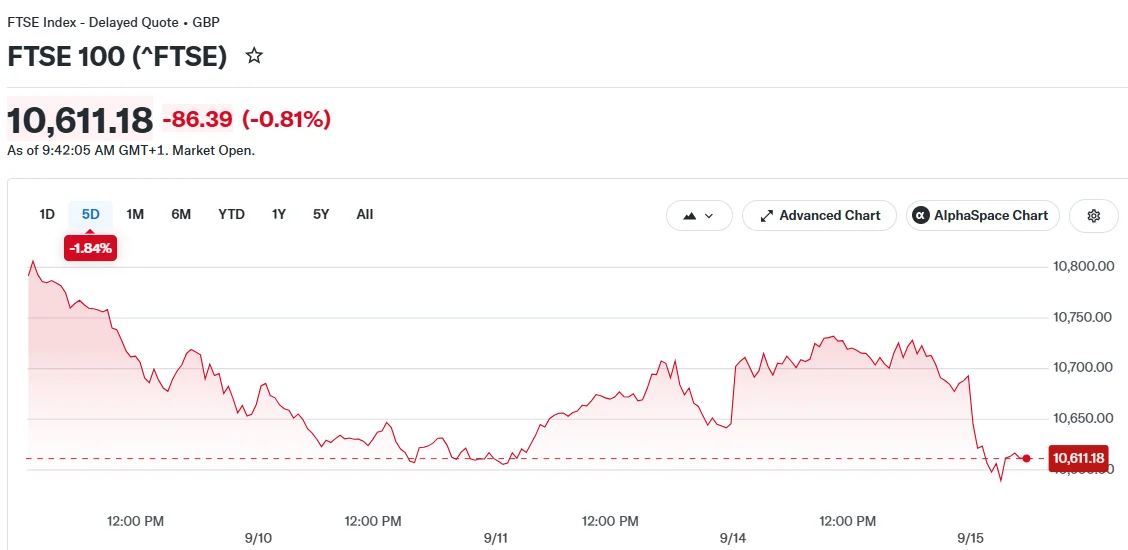
Britain’s benchmark FTSE 100 index declined 0.60%, while continental European markets also retreated with Germany’s DAX losing 0.36% and France’s CAC 40 dropping 0.64%. The British pound weakened 0.21% to trade at $1.3472 versus the US dollar.
The selloff unfolded as Brent crude advanced 1.67% to reach $107.42 per barrel. The price surge stemmed from a disruption to Saudi Arabia’s East-West pipeline system, which ING analysts suggested could maintain elevated pricing “well supported” for multiple weeks ahead.
WTI crude similarly gained 1.7% to settle at $103.09. Shipping traffic through the strategically important Strait of Hormuz dropped sharply to just four vessel transits on Monday from ten previously, based on Kpler data reported by Reuters.
Employment Figures Show Further Deterioration
Tuesday’s UK payrolled employment statistics revealed a decrease of 26,000 positions in August. This followed July’s downwardly revised decline of 19,000, pushing PAYE employment 0.5% beneath year-ago levels.
The figures significantly undershot Capital Economics’ projection of a 5,000 increase, representing a notable disappointment.
The private sector bore the brunt of job losses, shedding 34,000 positions in August and registering a 0.8% year-over-year contraction. Retail and hospitality sectors experienced particularly steep annual declines exceeding 3%.
Available job positions continued their downward trajectory, decreasing to 702,000 during the three months ending in August from 706,000 previously. This represents the weakest level outside pandemic disruptions in more than ten years.
Annual earnings growth including bonuses moderated to 3.9% in July from June’s 4.2% reading. Regular pay growth remained unchanged at 3.5%, matching economist expectations.
Capital Economics noted the softening employment landscape reinforces expectations that inflationary pressures stemming from elevated energy prices will stay contained. The consultancy suggested there’s a meaningful probability the Bank of England will leave rates unchanged at 3.75% this week or potentially avoid increases altogether.
ING forecasts the Bank’s Monetary Policy Committee will vote 6-3 in favour of maintaining current rates.
Artificial Intelligence Regulation Concerns Mount
Beyond economic releases, emerging divisions over artificial intelligence governance contributed to market nervousness.
Anthropic’s CEO Dario Amodei advocated for enhanced protective measures governing sophisticated AI systems, including independent third-party evaluations. He cautioned that the technology risks breaking free from human oversight and triggering catastrophic consequences.
OpenAI’s Sam Altman and Elon Musk endorsed a measured development strategy. US President Donald Trump resisted calls to decelerate progress, arguing restrictions could undermine competitiveness against Chinese AI enterprises.
In corporate developments, Trustpilot announced first-half revenues rose 23% to reach $151.4 million. Kier Group disclosed full-year revenues of £4.39 billion, representing a 7.5% increase, alongside a record £11.9 billion order backlog entering 2027.
Gold futures retreated 0.52% to $4,328.87, with ING cautioning that precious metals remain “vulnerable” ahead of Wednesday’s Federal Reserve policy announcement.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants