


TLDR
- The greenback index remained stable around 101.14, approaching a two-month peak, with expectations of a 1.7% gain for the month.
- Brent crude surged over 3% to exceed $107 per barrel following the collapse of US-Iran diplomatic negotiations.
- Traders now assign a 65% probability to a Federal Reserve rate increase at the late October policy meeting.
- Japan’s currency appreciated to approximately 156.75 against the dollar after officials signaled support for yen strength.
- Australia’s central bank is anticipated to lift its benchmark rate to 4.60% in Tuesday’s decision.
The US dollar maintained its position near a two-month peak during Monday’s session as market participants monitored escalating tensions between Washington and Tehran that have sent crude oil prices climbing.
The dollar index, which tracks the greenback’s performance versus a basket of major global currencies, remained anchored around the 101.14 level throughout Monday’s trading hours.
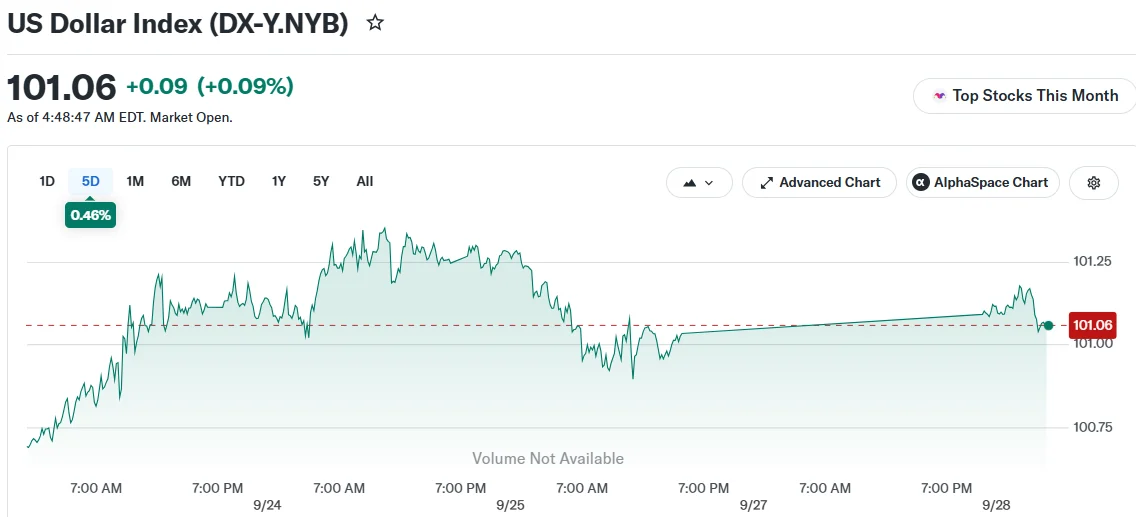
The benchmark is positioned to record a 1.7% monthly advance, which would mark its strongest monthly showing since the summer period.
Crude Markets Surge Following Diplomatic Breakdown
Brent crude contracts advanced more than 3% during Monday’s session, pushing prices beyond the $107 per barrel threshold.
The rally followed President Trump’s decision to walk away from proposed diplomatic arrangements with Iranian officials. The abandoned agreement would have sought to de-escalate regional tensions and restore normal shipping operations through the Strait of Hormuz.
Growing concerns about energy availability have intensified inflation pressures, prompting market participants to anticipate a more aggressive monetary policy stance from the Federal Reserve in upcoming decisions.
Longer-dated US government bond yields have continued their ascent, providing additional tailwinds for dollar strength.
“The greenback could overshoot in the near term if energy market tensions persist and inflation risks continue to build,” said Sim Moh Siong, FX strategist at OCBC. The bank still expects a moderate dollar rally by year-end.
The European common currency edged lower to approximately $1.138, hovering near its weakest level in two months and tracking toward a 2% monthly decline.
The British pound remained positioned around $1.325, close to the three-month trough recorded in the previous week. Bank of England chief Andrew Bailey has recently cautioned about the potential for additional monetary tightening.
October Rate Hike Probability Increases Before Critical Data Releases
The coming days will deliver several pivotal economic indicators. Wednesday brings the PCE inflation gauge, while Friday’s calendar features the monthly employment report.
Both releases are anticipated to reinforce the argument for continued policy normalization by the Federal Reserve. Current market pricing reflects a 65% likelihood of a 25-basis-point rate adjustment at the October 28 policy gathering.
The central bank implemented a rate increase at its most recent September meeting. Market analysts suggest that incoming economic data could strengthen conviction for additional tightening measures.
“Data could re-emerge as a primary driver for the dollar this week,” said ING FX strategist Francesco Pesole.
Manufacturing activity figures from China are scheduled for Wednesday release, arriving before the nation’s National Day holiday period. Euro area inflation statistics are slated for Friday publication.
The Japanese currency strengthened to roughly 156.75 versus the dollar following remarks from Japan’s senior currency official, Atsushi Mimura, regarding recent discussions about yen valuation.
Japanese and American financial authorities indicated last week their intention to enhance coordination on foreign exchange matters. Meanwhile, Japan’s latest data showed service sector price pressures accelerated to their fastest annual rate in more than two years during August.
These figures may bolster arguments for additional monetary tightening by the Bank of Japan in future deliberations.
The Australian currency traded at $0.7016 ahead of Tuesday’s Reserve Bank of Australia policy announcement. Economists widely expect a 25-basis-point increase that would bring the cash rate to 4.60%, representing a level not seen in nearly 15 years.
China’s offshore yuan firmed marginally to 6.7159 per dollar following the conclusion of a three-day bilateral summit between President Trump and Chinese leader Xi Jinping that yielded limited concrete outcomes.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


