Key Takeaways
- PLTR currently sits at $192.35, approximately 8% beneath its peak of $207.52.
- Quarterly revenue soared 93% year-over-year to reach $1.94 billion, driven by government contracts.
- Full-year revenue outlook increased to between $8.15 billion and $8.16 billion.
- Wall Street shows mixed sentiment: 23 Buy ratings, 10 Hold ratings, 3 Sell ratings, average target $195.33.
- British authorities are examining domestic options to replace Palantir systems in healthcare and defense sectors.
Palantir (PLTR) shares are currently changing hands around $192.35, positioned roughly 8% under the 52-week peak of $207.52. The equity has demonstrated consistent upward movement from levels near $160 recorded in August.
Palantir Technologies Inc., PLTR
This recent appreciation follows another impressive quarterly performance. The company delivered $1.94 billion in total revenue during the most recent period, representing a 93% increase compared to the same quarter last year.
Government revenue within the United States expanded at an even more aggressive clip, climbing 90% to hit $809 million. In response to this momentum, executives lifted their full-year revenue projection to approximately $8.15-$8.16 billion.
This represents a substantial upgrade from previous estimates. The revision demonstrates that Palantir’s artificial intelligence initiatives are converting into actual customer commitments rather than remaining in experimental phases.
Defense contracts and sovereign AI expansion accelerate
The U.S. Department of Defense designated Palantir’s Maven AI platform as an official program of record during the first half of this year. This classification embeds the software more permanently within military infrastructure.
Additionally, Palantir secured a $300 million contract with the U.S. Department of Agriculture. The company continues layering fresh government agreements atop its existing revenue base.
The sovereign AI segment represents an emerging growth vector. Palantir joined forces with Armada to integrate its Sovereign AI Operating System with customer-controlled data centers that operate independently from public cloud infrastructure.
This architecture enables government entities and enterprises to maintain complete jurisdiction over their AI frameworks and sensitive information. It marks a meaningful departure from dependence on platforms like AWS or Azure for computational resources.
The company has deepened its collaboration with Fujitsu as well, which is implementing AIP and Foundry solutions. Fujitsu has already leveraged this technology to integrate information across more than 3,000 suppliers and 18 manufacturing facilities for a client in Japan.
International challenges emerge alongside valuation controversy
Not all developments have been favorable internationally. Reports indicate UK government officials are evaluating British-based alternatives to Palantir for portions of NHS and military infrastructure projects.
Research published by the Financial Times revealed that over 20 NHS trusts have discontinued using certain Palantir waiting-list management tools. This development represents a genuine setback to the company’s global growth narrative.
MarketBeat data shows 36 analysts covering the stock. The breakdown includes 23 Buy or Strong Buy ratings, 10 Hold ratings, and 3 Sell ratings, producing a Moderate Buy consensus overall.
The consensus price target stands at $195.33, marginally above current trading levels. Individual targets span from $255 on the high end down to $80 on the low end, illustrating the wide divergence between optimistic and pessimistic views.
UBS and DA Davidson both upgraded their price objectives to $250 in recent weeks. Rosenblatt maintained its $225 target, while Goldman Sachs preserved a Neutral stance.
The central debate centers on valuation metrics. According to MarketBeat, Palantir trades at approximately 162 times earnings with a market capitalization exceeding $450 billion.
That represents a premium multiple for any software enterprise, regardless of growth trajectory. The optimistic thesis depends on Palantir maintaining near-90% revenue expansion for an extended period to validate current pricing.
From a technical perspective, PLTR encounters resistance between $198 and $205, a zone encompassing both an ascending channel boundary and prior selling pressure. A decisive close above this region could establish a runway toward $220-$225.
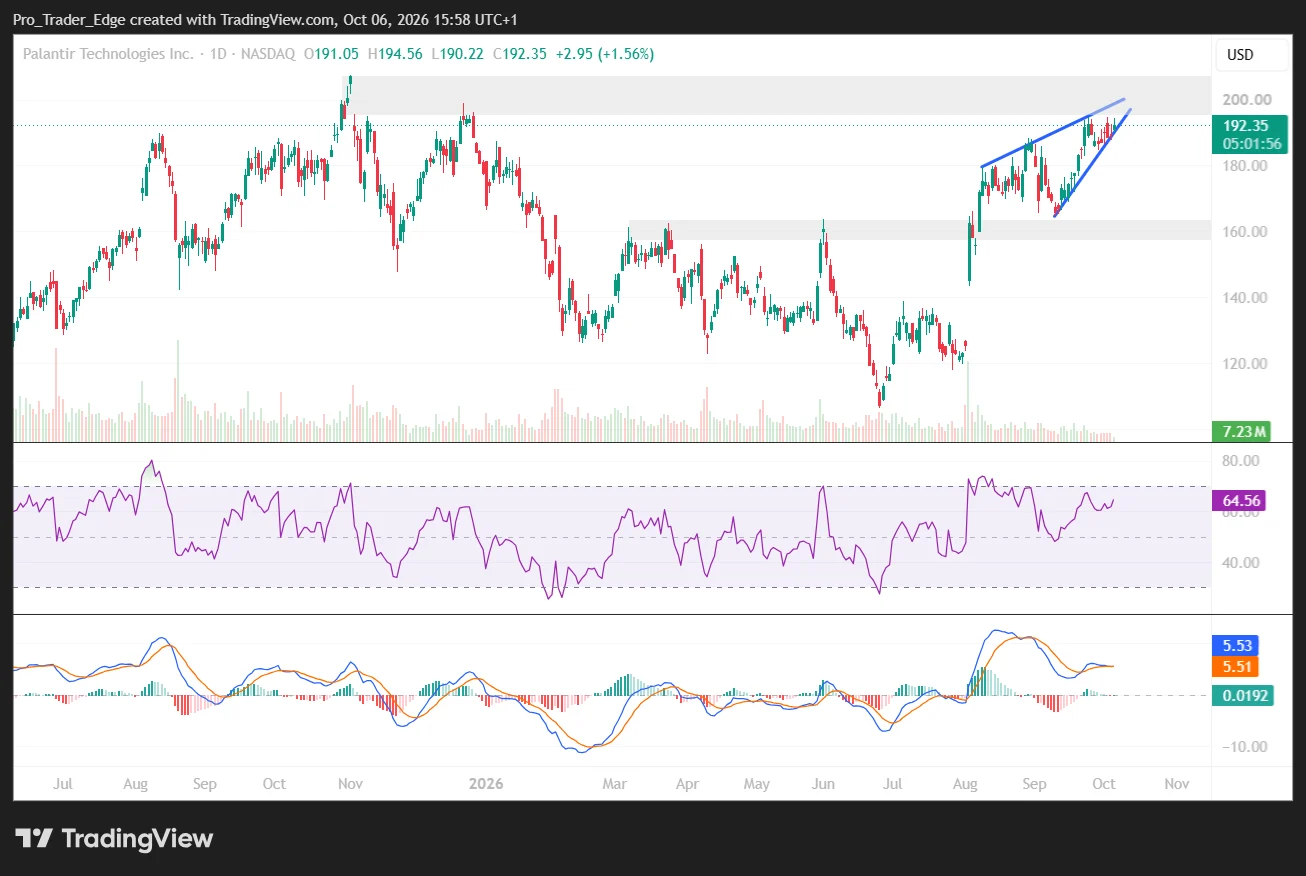
Initial support exists around $180 to $183, where the near-term trend line currently intersects. A violation below $180 would increase the probability of a more substantial retracement toward $160.
The Relative Strength Index currently registers 64.56, indicating solid momentum without reaching overbought territory. The MACD indicator has recently crossed into positive territory, though the histogram shows minimal divergence.
Trading volume has remained relatively subdued during the recent push toward $200. A breakout accompanied by heavier volume would signal greater conviction than one occurring on thin participation.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants