TLDR
- Both the S&P 500 and Nasdaq notched fresh all-time highs this week even as the 10-year Treasury yield holds above 5%.
- Corporate earnings are projected to grow more than 30% compared to the prior year, providing support despite elevated borrowing costs.
- Nvidia’s valuation is approaching the $6 trillion mark, propelled by continued investment in artificial intelligence infrastructure.
- Tuesday’s trading session saw gains across every S&P 500 sector, indicating the advance extends well beyond mega-cap technology stocks.
- Market strategists remain divided, with projections ranging from the S&P 500 climbing to 10,000 by 2030 to potentially retreating to 5,000 by 2027.
Financial markets hit new milestones this week despite government bond yields hovering near their highest levels in more than two decades. The S&P 500 and Nasdaq both registered record closes on Tuesday, while the Dow Jones Industrial Average also advanced.
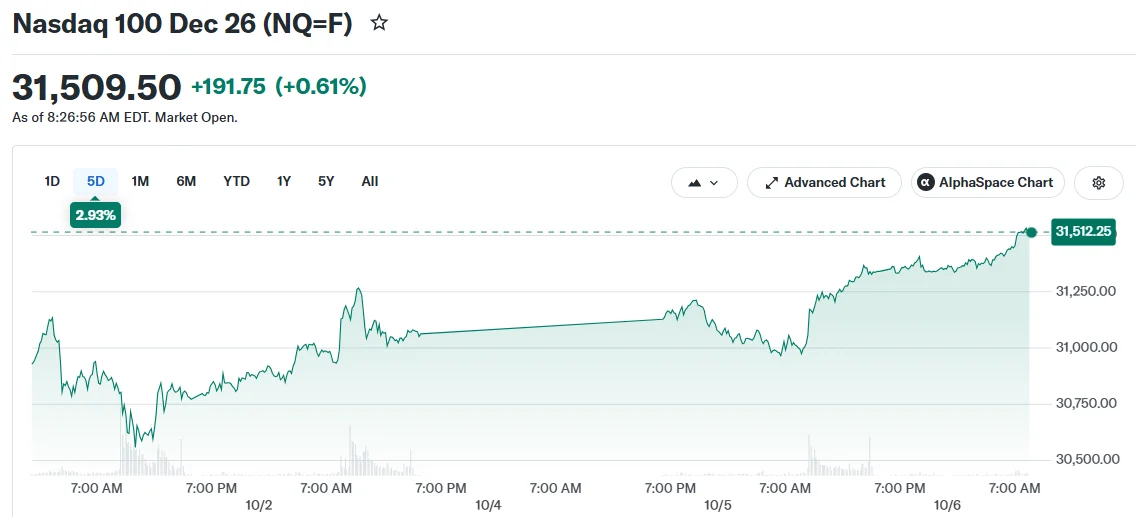
Meanwhile, the benchmark 10-year Treasury yield continues trading above the 5% threshold, recently climbing to levels last witnessed in 2002.
Under typical market conditions, elevated bond yields create headwinds for equity valuations. When Treasury securities offer attractive risk-free returns, investors have less incentive to allocate capital toward volatile stocks. Growth-oriented technology companies generally feel this pressure most acutely.
Yet the current environment is proving different.
Robust Profit Growth Provides Market Support
The primary factor sustaining the equity rally is corporate earnings momentum. Wall Street analysts are forecasting that S&P 500 constituent companies will deliver profit growth exceeding 30% on a year-over-year basis.
Artificial intelligence companies are leading this expansion. Nvidia’s stock price climbed again during Tuesday’s session, bringing the semiconductor giant’s total market capitalization within striking distance of $6 trillion.
Additional chipmakers also posted gains as market participants continue anticipating sustained investment in data center capacity and AI computing resources.
The market’s strength extends well beyond a handful of technology titans. Every one of the S&P 500’s 11 sectors posted advances on Tuesday. Utilities and real estate names performed particularly well as Treasury yields pulled back modestly from recent peaks.
The Significance of Rising Treasury Yields
The 10-year Treasury yield recently climbed to approximately 5.34%, marking its highest reading in roughly 24 years. This increase reflects market concerns about persistent inflation, expanding government debt levels and economic resilience.
Elevated yields present a challenge for equity markets. When investors can secure returns above 5% from government-backed securities, the relative attractiveness of stocks diminishes.
Rising rates also increase financing costs across the economy for corporations, households and government entities. This dynamic particularly affects growth stocks, whose valuations rely heavily on profit projections extending years into the future.
As interest rates climb, the present value of those anticipated future earnings decreases. Until now, powerful earnings growth has been sufficient to offset this valuation pressure.
Some market observers are now questioning whether 6% yields, rather than the current 5% level, might represent the true tipping point where equities face meaningful headwinds.
Expert opinions about the market’s trajectory diverge dramatically. With the S&P 500 trading near 8,000, certain strategists project the index could climb to 10,000 before the decade ends.
Conversely, other analysts paint a more cautious picture. Panmure Liberum recently published research suggesting the S&P 500 might retreat to approximately 5,000 by late 2027 if inflation remains sticky and interest rates stay elevated.
This divergence in professional forecasts underscores the delicate balance characterizing current market conditions.
Market participants will closely monitor upcoming third-quarter earnings releases, Federal Reserve policy signals, inflation readings and Treasury market movements in coming weeks. Continued strong earnings combined with moderating yields could propel the S&P 500 well beyond 8,000.
The greater risk scenario involves disappointing corporate results coinciding with further yield increases.
For the moment, record equity valuations signal that investors maintain confidence that corporate profit growth will continue outpacing the burden of higher financing costs.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants