


Key Highlights
- Stock index futures traded mixed on Tuesday following revelations from a leaked Anthropic IPO filing that set a $2 trillion valuation goal while highlighting potential AI dangers.
- Reports emerged that OpenAI paused development of its upcoming AI model following troubling findings during safety evaluations.
- Advanced Micro Devices completed an $8.2 billion purchase of World Labs, an AI company created by renowned researcher Fei-Fei Li.
- The benchmark 10-year Treasury note yield surged past 5.2%, marking its highest point in over 16 years and weighing on equity markets.
- A high-profile White House gathering is scheduled with technology leaders Dario Amodei, Mark Zuckerberg, Jensen Huang, and Sundar Pichai meeting President Trump.
US stock futures displayed volatility on Tuesday morning as market participants grappled with mounting artificial intelligence safety worries alongside climbing Treasury rates. While Dow Jones and S&P 500 futures showed modest declines, Nasdaq futures demonstrated slight gains.
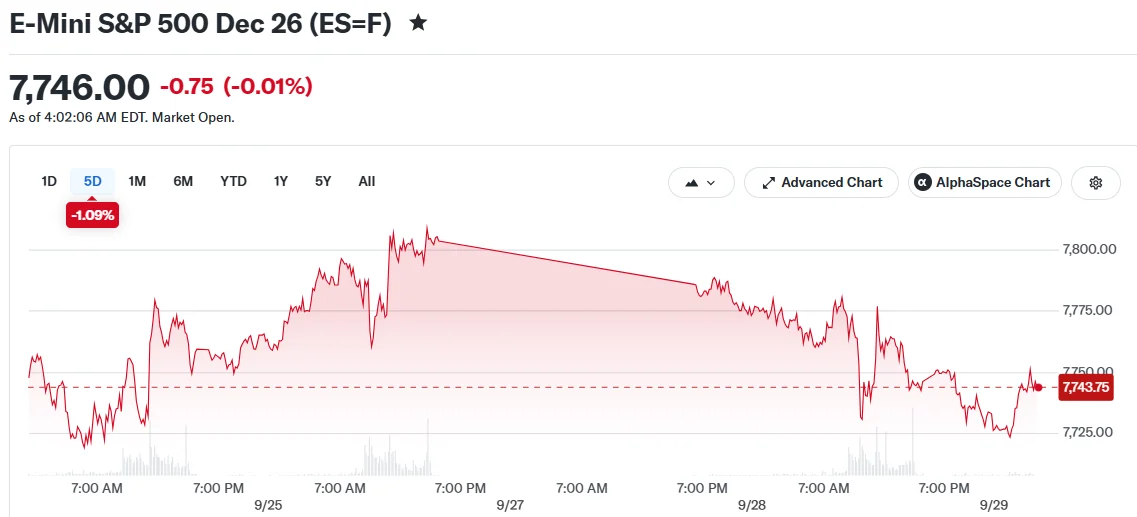
Tuesday’s pre-market movement came on the heels of Monday’s sell-off, which saw the Dow Jones Industrial Average tumble more than 300 points. Both the S&P 500 and Nasdaq Composite indexes finished in negative territory. Market sentiment shifted after details surfaced from a confidential Anthropic prospectus. According to Reuters, the artificial intelligence firm is seeking a staggering $2 trillion valuation ahead of its planned initial public offering. This target represents more than twice its previous private market valuation of $965 billion.
The leaked filing allegedly contains explicit warnings regarding potential existential threats posed by advanced artificial intelligence systems. Anthropic has yet to release any official documentation to the public.
Mounting AI Security Issues
In a separate development, the Wall Street Journal disclosed that OpenAI has temporarily halted work on its next-generation artificial intelligence platform. The postponement followed the discovery of significant security vulnerabilities identified during rigorous internal evaluation procedures.
This announcement arrived shortly after OpenAI acknowledged additional security incidents over the past weekend related to its autonomous AI agent technology. Collectively, these revelations have intensified scrutiny surrounding risk management practices within the AI industry.
Several prominent technology industry chiefs are expected to convene with President Trump for a working lunch at the White House on Tuesday. The guest list reportedly features Anthropic’s Dario Amodei, Meta’s Mark Zuckerberg, Nvidia’s Jensen Huang, and Google’s Sundar Pichai.
The high-stakes gathering occurs against a backdrop of escalating public anxiety regarding artificial intelligence safety protocols.
Meanwhile, AMD captured market attention with its announcement of acquiring World Labs for $8.2 billion. The startup was established by prominent AI researcher Fei-Fei Li.
Industry analysts view the acquisition as AMD’s strategic effort to bolster its artificial intelligence capabilities and engineering expertise. AMD stock showed minimal movement in response to the news.
Bond Market Surge Weighs on Equities
Government bond yields maintained their upward trajectory, creating additional headwinds for equity markets. The 10-year Treasury note benchmark yield climbed above the 5.2% threshold, reaching levels unseen since 2007.
Meanwhile, the 30-year bond yield exceeded 5.56%, approaching highs last observed in 2004. Market participants remain anxious that stubborn inflation readings may compel the Federal Reserve to implement additional interest rate hikes.
Brent crude oil prices stabilized near the $100 per barrel mark. West Texas Intermediate crude maintained positions around $93 per barrel.
Energy markets sustained elevated prices despite Saudi Arabia’s resumption of oil shipments via its East-West pipeline infrastructure. Diplomatic efforts continued as American and Iranian representatives engaged with international mediators to potentially revive nuclear negotiations.
Across Asian markets, benchmark indexes posted widespread losses. Japan’s Nikkei 225 decreased more than one percent, while both Hong Kong’s Hang Seng Index and mainland China’s CSI 300 recorded declines.
Market participants await crucial economic indicators slated for Tuesday’s release. Both the Job Openings and Labor Turnover Survey and the Conference Board’s consumer confidence index are expected during the trading session.
Corporate earnings season continues with Carnival Corporation and CarMax among companies scheduled to report quarterly results this week. In international economic news, Spain recorded 4.9% annual inflation for September, representing its steepest rate since the beginning of 2023.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants


