Key Takeaways
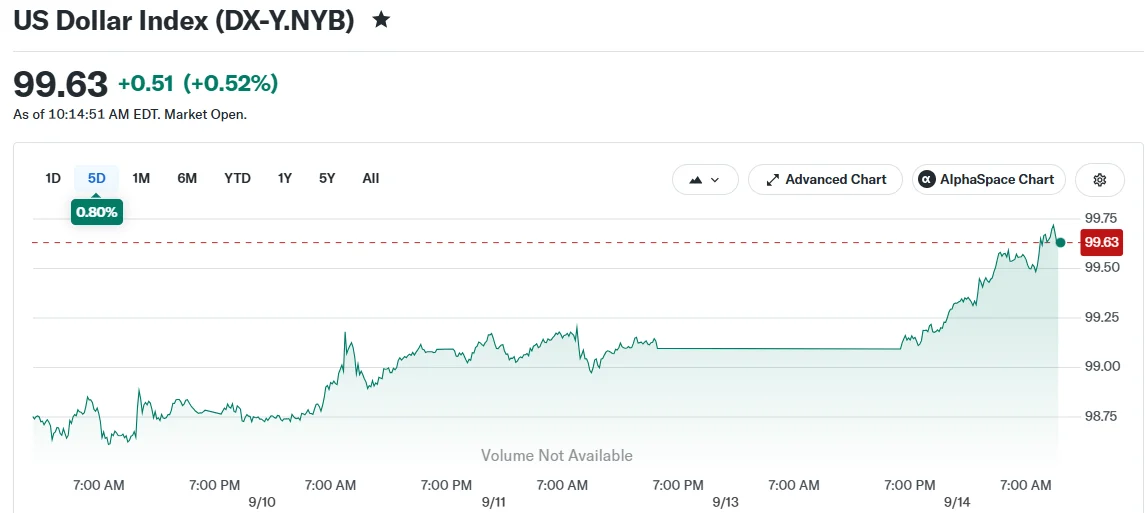
- The Dollar Index advanced 0.55% to reach 99.55, approaching a two-week high on Monday’s trading session
- Traders are assigning an 86% probability to a 25 basis point Fed rate increase at this week’s policy meeting
- The euro declined 0.5% to $1.1500 following the European Central Bank’s decision to raise rates to 2.50% last week
- Brent crude oil surged 3% to approximately $112 per barrel after attacks on Saudi pipeline facilities
- Despite current dollar momentum, Bank of America forecasts range-bound performance through the end of the year
The U.S. dollar strengthened on Monday as market participants increasingly positioned for a Federal Reserve rate increase this week, spurred by persistent inflation readings and a renewed surge in crude oil prices.
The Dollar Index, which measures the greenback’s performance against a basket of six major global currencies, rose 0.55% to reach 99.55. This advance ended a two-week streak of marginal declines.
CME FedWatch data now indicates that market participants are pricing in an 86% likelihood of a 25 basis point interest rate increase at the Federal Reserve’s upcoming September 15-16 policy meeting.
Persistent Inflation Reinforces Rate Hike Outlook
Last Friday’s consumer price index release maintained pressure on Federal Reserve policymakers. Headline inflation remained steady at 3.4%, while core CPI increased 0.3% on a month-over-month basis.
The data briefly drove the 10-year Treasury yield above the 5% threshold. Swap market participants are also factoring in substantial odds for an additional rate increase in December.
The euro weakened 0.5% to $1.1500, marking a near two-week low. Market participants are balancing eurozone stagflation concerns against dollar strength, following last week’s European Central Bank rate decision to lift rates to 2.50%.
The Japanese yen retreated modestly on Monday, with the dollar advancing 0.65% to approximately 154.55. Nevertheless, the yen maintains a 4% gain for September, trading near seven-month peaks reached last week.
The Bank of Japan is broadly anticipated to increase its policy rate by 25 basis points on Friday, lifting it to 1.25%. Expectations for accelerated tightening, combined with Tokyo’s unprecedented $96.4 billion currency market intervention, have driven speculators to establish net long positions on the yen for the first time since February.
Energy Market Volatility Intensifies Currency Movements
Brent crude rallied approximately 3% on Monday to approach $112 per barrel. Recent attacks on Saudi Arabian pipeline infrastructure and Houthi military activity in the Red Sea region have constricted Persian Gulf oil supplies.
This week presents an exceptionally packed calendar for central bank observers. The Federal Reserve convenes on Wednesday, the Bank of England gathers on Thursday, and the Bank of Japan meets on Friday.
Notwithstanding Monday’s dollar appreciation, Bank of America anticipates constrained upside potential going forward. The institution projects the dollar will remain range-bound through year-end, with the exception of movements versus the yen.
BofA analysts observed that dollar sentiment has remained subdued since Fed Chair Warsh’s July press conference, during which markets interpreted a lack of concrete strategy for addressing inflation above the central bank’s target.
The dollar has additionally struggled to gain traction despite climbing energy costs, which historically provide support for the currency. Conflicting messages from Fed officials, including more accommodative remarks from Williams and Waller, have contributed to market uncertainty.
With markets now pricing in more than three rate increases, Bank of America contends that the threshold for the Fed to exceed market expectations remains elevated.
The firm released its analysis on September 8, 2026, in a research note titled “G10 FX back-to-school: dollar unloaded.”
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants