
TLDR:
- Saylor proposes five core rights: create, issue, custody, transfer, and use digital assets freely.
- He sets a goal of financing 10 million new companies through faster digital token issuance.
- Saylor urges banks to custody Bitcoin and extend credit against it under clearer capital rules.
- He criticizes the CLARITY approach and projects a $100 trillion digital asset industry ahead.
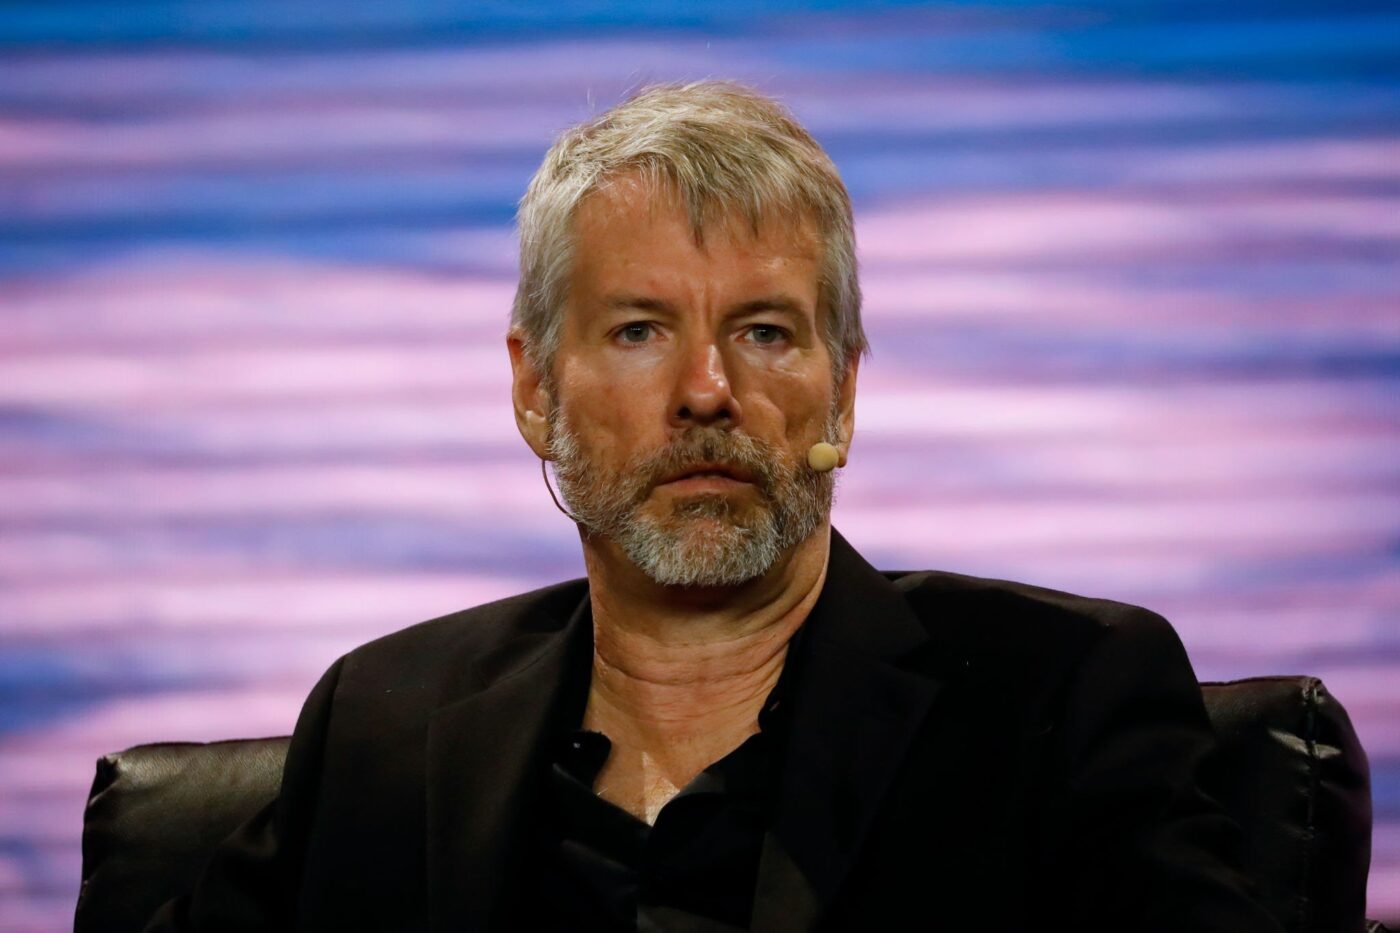
Digital asset rights formed the center of Michael Saylor’s policy remarks at the Bitcoin Policy Institute’s Freedom Tech DC summit.
Saylor spoke with Conner Brown about a framework built on five freedoms. These include the right to create, issue, custody, transfer, and use digital assets.
He argued that a more productive economy, driven by artificial intelligence, needs better money and better capital markets. Growth in AI output should be matched by growth in financial access, he said.
Five Freedoms Anchor the Policy Framework
Saylor’s proposal rests on treating digital asset rights as belonging to both individuals and corporations. “Freedom starts with the ability to act,” Saylor said.
Each of the five freedoms serves a distinct purpose, from creating new financial instruments to spending and borrowing against holdings.
The framework also calls for financing structures that support new business formation. Saylor set a goal of enabling 10 million new companies to raise capital through digital tokens.
He described current issuance rules as too costly and complex for entrepreneurs without extensive legal resources. Lowering that cost, he said, would let more founders reach investors directly.
Competition among digital dollar providers formed another part of the discussion. Saylor said banks, fintech companies, and technology platforms should have a clear path to offer dollar-backed digital products.
He also argued that issuers should be permitted to compete on yield. Restrictions that favor institutions paying little interest work against customers, he said.
Bitcoin’s integration into banking and insurance drew separate attention. Saylor called for banks to custody Bitcoin and extend credit against it.
He pointed to the Basel framework’s capital treatment of cryptoasset exposures as an area needing review. Rules should reflect actual risk, he said.
Privacy, Compliance, and Regulatory Priorities
Financial privacy featured prominently in Saylor’s remarks on ordinary transactions. He proposed that lawful transactions below a meaningful threshold should not trigger routine reporting requirements.
Saylor referenced the outdated $10,000 currency-transaction threshold set in 1972 as an example needing inflation adjustment.
Portable compliance credentials also appeared as a policy recommendation. Saylor described repeated identity verification across financial counterparties as costly and inefficient for investors.
He suggested reusable, interoperable credentials could reduce onboarding costs while preserving provider responsibility for monitoring risk. Lower costs, he added, would help new firms compete for customers.
Tax treatment of everyday digital asset spending was another focus area. Saylor argued that a meaningful de minimis exemption would remove the burden of calculating gains on routine purchases. He said thresholds should scale with inflation and eliminate needless transaction-by-transaction recordkeeping.
On regulatory strategy, Saylor pointed to the SEC, CFTC, Treasury, and White House as the near-term path. He criticized the CLARITY approach for emphasizing restrictions over usefulness.
Saylor projected the digital asset industry could reach $100 trillion in value if policy expands rather than limits ownership rights.